
Buyer's guide
How to buy a shop condo
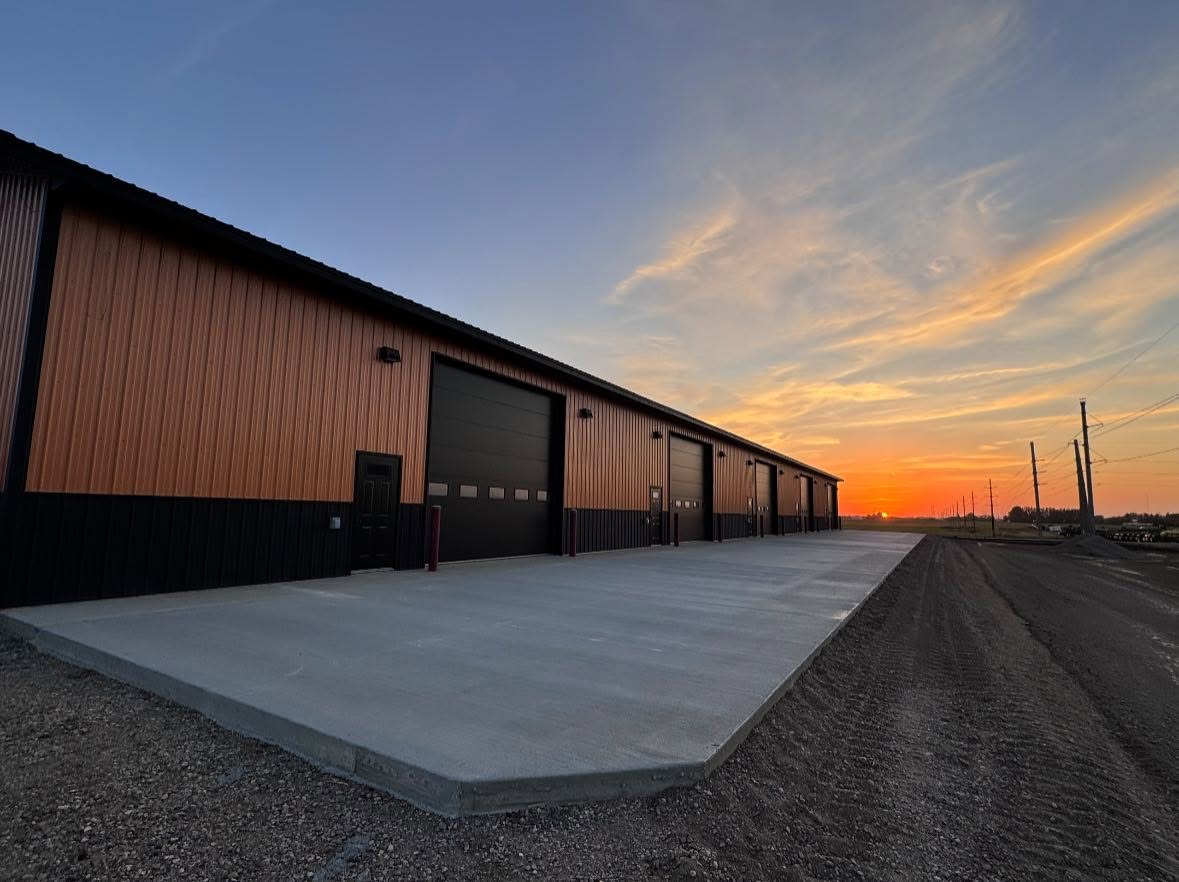
Buying a unit at 30th Ave NE and Hwy 2, Rugby, ND 58368 works like buying any other piece of commercial real estate: a lender, an appraisal, a title company, and a closing. Here is the order it happens in and what you pay along the way. Nothing here is a loan offer — your bank sets your terms.
The steps
01
Call or text and say what you need
Square footage, door height, whether you want to buy or rent, and when you need it. One call usually settles which of the three sizes fits.
02
Walk the unit
Come out to the corner of 30th Ave NE and Hwy 2 and look at the slab, the door, the heat, and the utility room. Bring a tape measure and the machine you plan to park inside.
03
Talk to a lender
Most buyers finance through a local bank or credit union as commercial real estate. Ask for a term sheet before you write an offer so you know your payment, your down payment, and your closing costs.
04
Write the purchase agreement
Price, unit number, closing date, and financing terms. You will also get the condo declaration and the HOA dues so you can read what the association covers.
05
Financing and title work
The lender orders an appraisal and title work. This is usually the longest stretch, and it is mostly waiting on third parties.
06
Close and get the keys
Sign at the title company, pay your down payment and closing costs, and the unit is yours. Put the electric meter in your name and move in.
What it costs
Financing
A shop condo is commercial real estate, so it is financed like commercial property rather than a house. Local banks and credit unions in Rugby, Minot, and Devils Lake write these loans, and terms vary by lender and by borrower. Some buyers finance through their business, some buy with cash, and some lease first and buy later.
Down payment
Commercial lenders normally want more down than a home loan does. Your bank sets the number based on the loan, your business, and the appraisal, so get that figure from them early — it is the piece that decides how much unit you can take.
Closing costs
Expect the usual commercial closing items: appraisal, title insurance and title company fees, recording fees, loan origination, and prepaid amounts. Your lender's loan estimate lists them line by line before you sign anything.
Monthly costs after closing
Your loan payment, $150 a month in HOA dues, electricity on your own meter, and insurance on your contents. The dues cover the shared site and the association's insurance on the building exterior.
Purchase prices today
- 60' x 100' — From $649,900 + $150/mo dues
- 40' x 60' — From $279,900 + $150/mo dues
- 40' x 40' — From $217,900 + $150/mo dues
Prices change; call Dave at 701-771-2670 for what is open and current.
Included in your dues
- Gravel road maintenance
- Snow removal
- Lawn care and weed control
- Sanitation dumpsters
- Water and sewer service
- Association insurance on the building exterior
You pay separately
- Electricity (private meter)
- Contents insurance
More answers on the FAQ page, or see every unit with photos and pricing.